- Extreme rainfall and flooding
- Water intrusion and mold
- Tropical storm wind
- Tsunami (usually excluded)
- Downtown Hilo
- Keaukaha
- Waiakea
- Kaumana
- Panaewa
- Wainaku
- Papaikou
Housing: Hilo has many older plantation-style and single-wall wood homes on post-and-pier foundations, mid-century subdivisions, historic downtown commercial buildings and a mix of newer homes upslope.
History: Hurricane Lane in August 2018 brought extreme rainfall and flooding to the Hilo area, and the town carries a long history of tsunamis, including 1946 and 1960.
Building in one of the wettest towns in the islands
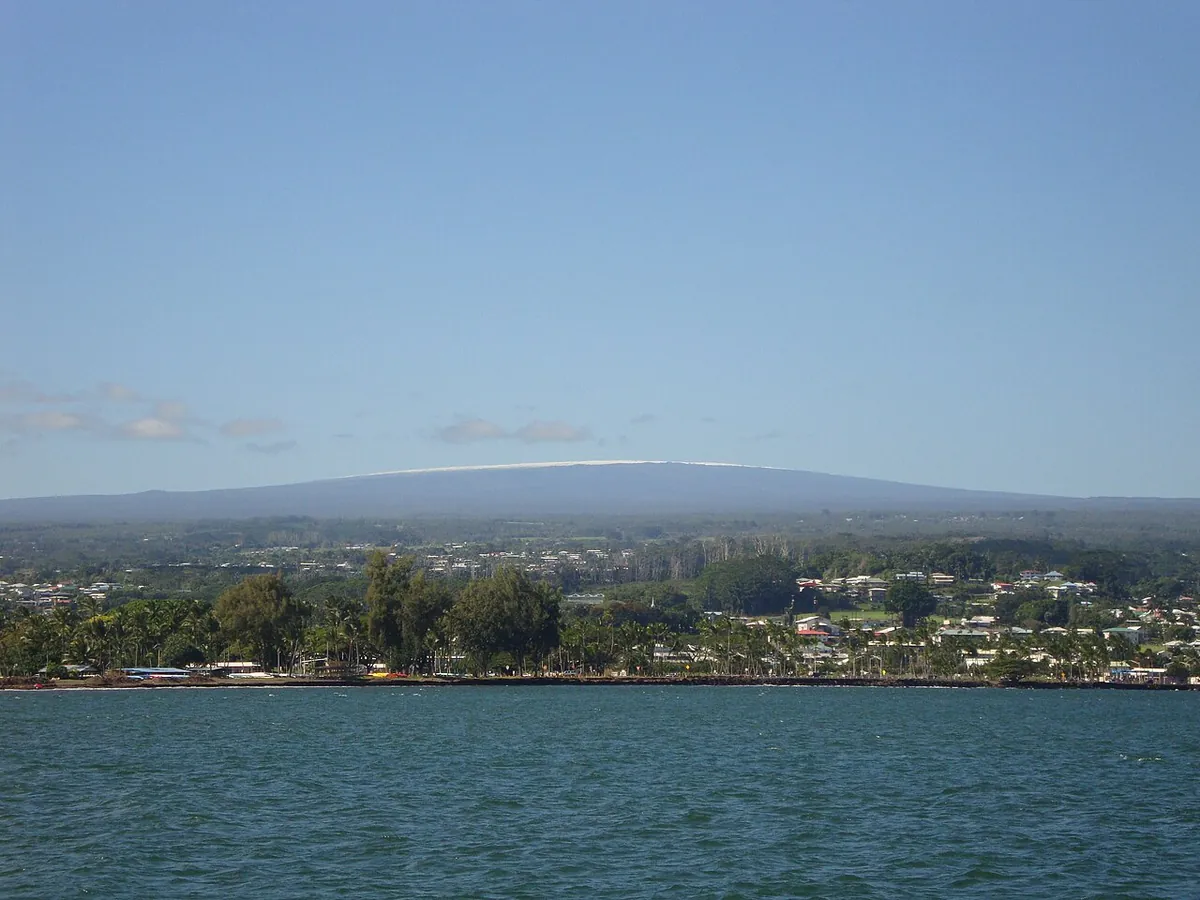
Hilo sits on the windward side of Hawaii Island, facing the trade winds and the rain they carry. That climate defines the housing. Older neighborhoods such as Wainaku, Keaukaha and parts of Waiakea are full of plantation-style homes, single-wall construction and raised floors on post-and-pier foundations, often with corrugated metal roofs. Kaumana and Panaewa mix older homes with newer construction on larger lots, some with rain catchment systems. Downtown Hilo has historic commercial buildings, many with apartments or offices above street-level shops.
Constant moisture makes rot, termites and mold a fact of life, and insurers know it. Many Hilo claim disputes come down to whether damage was sudden and covered or long-term and excluded.
Rain, storms and tsunami history
In August 2018, Hurricane Lane stalled south of the islands and poured extreme rainfall on East Hawaii, flooding streets, homes and gulches around Hilo. Heavy rain events and flash floods are recurring hazards here. Hilo’s bayfront is also known for the tsunamis of 1946 and 1960, which reshaped the town’s waterfront. Tsunami and flood damage are generally excluded from homeowners policies, so separate flood coverage matters in low-lying areas.
Common East Hawaii disputes
- Roof leaks during storms labeled as long-term deterioration.
- Mold remediation capped or excluded even when the water event was sudden and reported promptly.
- Termite-damaged framing found during repairs and removed from the scope entirely.
- Single-wall and post-and-pier homes priced with mainland framing assumptions.
- Estimates missing inter-island freight, General Excise Tax or the cost of scarce local labor.
How appraisal helps Hilo owners
Appraisal is designed for disputes about the amount of a covered loss. If your insurer accepts that a storm damaged your home but pays well below what East Hawaii contractors charge, the appraisal clause may allow each side’s appraiser – and an umpire if needed – to set the number. It does not decide coverage, so denials and exclusion disputes are questions for a Hawaii attorney.
Hawaii Insurance Appraiser scopes losses with an eye on how Hilo homes are actually built, including raised floors, single-wall framing and metal roofing, and prices them with freight and tax included. See our water damage claim appraisal and hurricane claim appraisal services, or read about GET and freight in estimates.
After any heavy rain event, photograph the damage, dry out what you can and keep receipts for fans, dehumidifiers and emergency repairs. Most policies require you to take reasonable steps to prevent further damage, and in Hilo’s humid climate prompt drying can be the difference between a water claim and a much larger mold problem.
Specialties available in Hilo
Every Hawaii Insurance Appraiser specialty is available to owners and associations in Hilo, including:
- Appraisal Clause Representation
- Homeowner Claim Appraisal
- Condo, AOAO & Commercial
- Roof & Hail Claims
- Kona Storm & High-Wind Claims
- Hurricane Claim Appraisal
- Water Damage Claims
- Fire & Smoke Claims
Questions from Hilo owners
Is flood damage from a Hilo rainstorm covered by my homeowners policy?
Surface water and flood are usually excluded from homeowners policies. Water that enters through a storm-damaged roof or a burst pipe is treated differently and is often covered.
My insurer says the damage in my Hilo home is from termites. What can I do?
Termite damage itself is typically excluded, but storm or water damage alongside it may still be covered. Ask the insurer to separate the causes, and consider an independent inspection.
Does my rain catchment system count in a claim?
A catchment tank and its components may be covered as part of the dwelling or other structures, depending on your policy. If they were damaged in a covered event, include them in your claim.