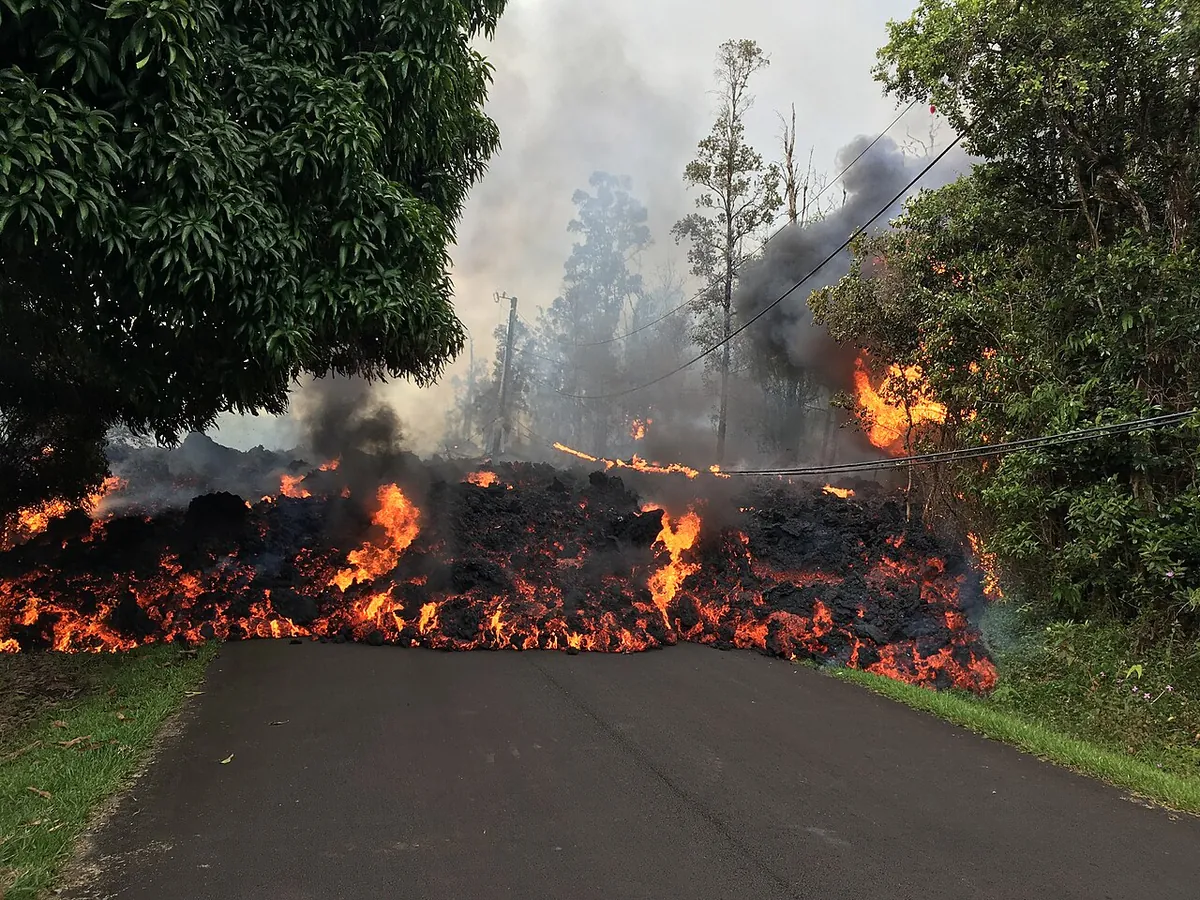
- Lava flow and volcanic activity
- Tree fall in tropical storms
- Heavy rain and water intrusion
- Volcanic gas and ash
- Pahoa
- Keaau
- Hawaiian Paradise Park
- Hawaiian Acres
- Orchidland Estates
- Hawaiian Beaches
- Nanawale Estates
- Leilani Estates
Housing: Puna is largely owner-built and modest wood-frame homes on large subdivided lots, many on post-and-pier foundations with metal roofs and rain catchment water systems.
History: The 2018 Kilauea lower East Rift Zone eruption destroyed hundreds of homes in Puna, Kalapana was overrun by lava in 1990, and Tropical Storm Iselle in 2014 brought down many trees across the district.
Insuring property in Puna
Puna is one of the fastest-growing parts of Hawaii Island and one of the most challenging to insure. Large subdivisions such as Hawaiian Paradise Park, Hawaiian Acres, Orchidland Estates, Hawaiian Beaches and Nanawale Estates were laid out decades ago on rain-forest land, and many homes there are owner-built wood structures on post-and-pier foundations, with corrugated metal roofs and rain catchment for water. Pahoa and Keaau serve as town centers, with older commercial buildings and homes.
Much of Puna lies in USGS lava hazard zones 1 and 2 on Kilauea’s East Rift Zone. Many private carriers decline those zones, so the Hawaii Property Insurance Association (HPIA), the state’s FAIR plan, writes basic property coverage for many owners here. HPIA policies can be narrower than a full homeowners policy, so it is worth reading yours closely.
Eruptions and storms
In 2018, the lower East Rift Zone eruption sent lava through Leilani Estates, Lanipuna Gardens, Kapoho and Vacationland, destroying hundreds of homes. Kalapana was overrun by lava in 1990. Puna also faces storm damage: Tropical Storm Iselle in 2014 toppled many trees, especially invasive albizia, onto homes, roads and power lines. Heavy rain is routine, and volcanic gas and ash can affect roofs, catchment systems and finishes.
Common Puna disputes
- Whether lava, ash or volcanic gas damage is covered under the specific policy form.
- Owner-built homes valued below their real replacement cost because they lack typical documentation.
- Tree-fall claims where removal and debris costs exceed what the insurer allows.
- Catchment tank and water system repairs omitted from the scope.
- Remote-site costs, travel time and limited contractor availability left out of pricing.
How appraisal can help
When a Puna loss is covered but the insurer’s valuation is low, the appraisal clause may allow an independent process to set the amount. That can matter for owner-built homes, where carriers sometimes rely on generic cost data that does not reflect real construction costs in rural East Hawaii.
Hawaii Insurance Appraiser documents construction methods, measures structures and prices repair or rebuilding with local labor, freight and General Excise Tax. Our volcanic ashfall and lava claims service explains how these losses are valued, and the appraisal readiness check helps you decide whether your claim is ready for appraisal.
Because many Puna homes are built without contractor records, start collecting what evidence you can: photos of the home over the years, receipts for lumber and roofing, building permits if any were pulled, and descriptions of the plumbing, electrical and catchment systems. Even partial records can make a meaningful difference in how a remote, owner-built home is valued.
Specialties available in Puna & Pahoa
Every Hawaii Insurance Appraiser specialty is available to owners and associations in Puna & Pahoa, including:
- Appraisal Clause Representation
- Homeowner Claim Appraisal
- Condo, AOAO & Commercial
- Roof & Hail Claims
- Kona Storm & High-Wind Claims
- Hurricane Claim Appraisal
- Water Damage Claims
- Fire & Smoke Claims
Questions from Puna & Pahoa owners
Does an HPIA policy in Puna cover lava damage?
HPIA policies are written for properties that private carriers often decline, but the specific perils covered depend on the policy form. Read the declarations and policy wording, and check current details with HPIA or your agent.
My Puna home is owner-built. Can it still be valued fairly?
Yes. An appraiser can document the materials and methods used and price what it would cost to repair or rebuild with comparable quality, even without contractor records.
Who pays to remove a tree that fell on my house in Puna?
Many policies pay for tree removal when the tree damages a covered structure, often subject to a separate sublimit. The amount allowed is a common point of dispute.