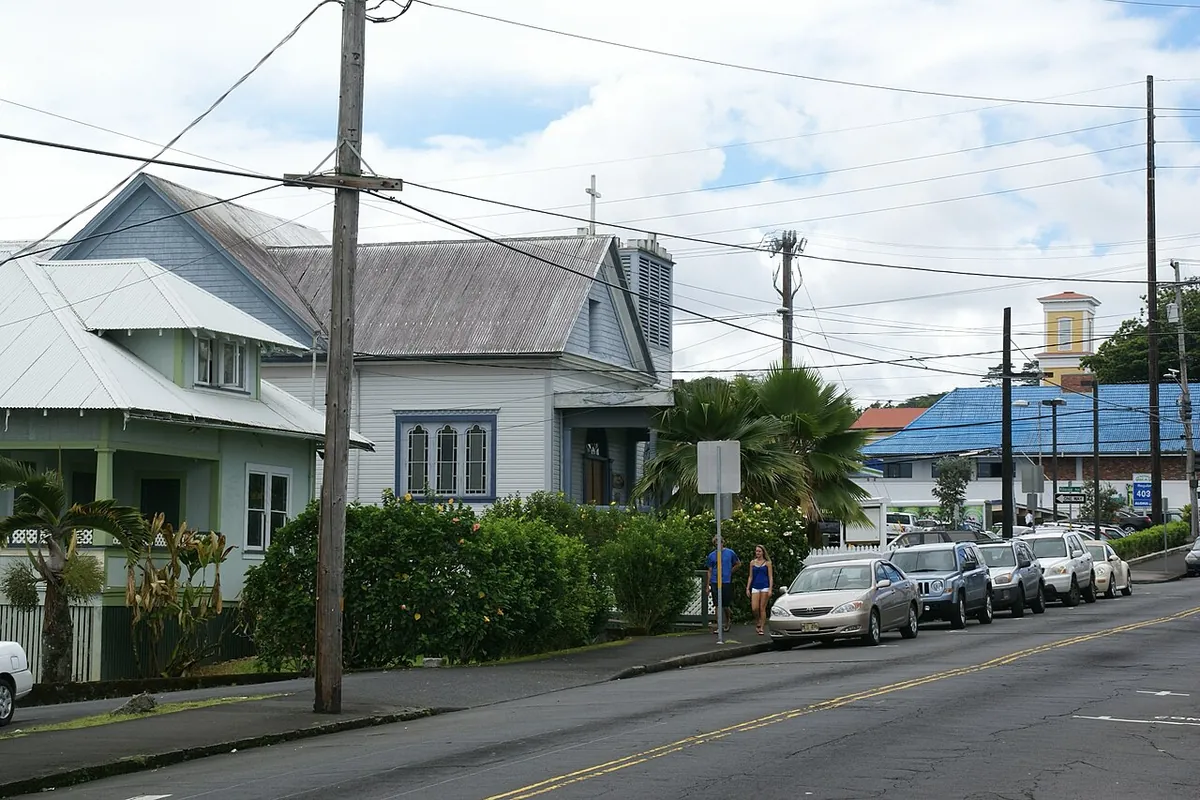
Roof claims look different in Hawaii
Corrugated and standing-seam metal is everywhere in the islands, alongside asphalt shingles on newer subdivisions and concrete or clay tile on higher-end homes. Hip roofs are common because they handle wind well. Each type fails differently, and each raises its own questions about repair versus replacement.
Hail is rare in Hawaii, but not impossible. The March 2012 Windward Oahu supercell produced the largest hailstone on record in the state, and isolated hail still shows up in strong winter storms. More often, roof claims follow high wind or wind-driven rain that finds its way through lifted panels, failed fasteners or damaged flashing.
What we measure and price
- Squares and pitch: accurate measurements, including waste, hips and ridges. Our roof pitch and squares estimator gives a quick first check.
- Panel profile and availability: whether a matching metal profile or tile is still made, and what happens when it is not.
- Underlayment and fasteners: what must be replaced alongside the visible damage, and what current code requires.
- Interior damage: ceilings, insulation and finishes harmed by water that came through the roof opening.
- Island pricing: freight for roofing materials, inter-island barge charges, crane or lift access, disposal and GET.
Repair, partial or full replacement
The biggest gap on most roof claims is whether a slope or the whole roof needs replacing. A repair the carrier calls reasonable may be impractical if new panels will not interlock with old ones, or if tile breakage during repair would be extensive. These are cost and feasibility questions an appraisal panel can weigh.
Wind-driven rain through the roof
Many policies cover rain damage to the interior only when wind first creates an opening in the roof or walls. That condition matters. We document the opening – lifted panels, torn flashing, missing ridge caps – along with the interior damage, so the panel can see how the water got in. Related claims are covered on our Kona storm and high-wind claims page.
Photos that help a roof appraisal
If it is safe, photograph the roof from the ground right after the storm, including any panels or caps that landed in the yard. Keep receipts for tarps and emergency repairs, and save a few damaged fasteners or panel pieces. Older photos of the roof, such as from a home purchase or a solar installation, help show its condition before the event and can answer a later argument about prior wear.
Roofs across the islands
We work on roofs from Kaneohe and Kailua, where trade winds hit hardest, to Hilo and Hamakua with their heavy rainfall, to the hot, dry leeward slopes of Kihei and Kapolei. Hawaii Insurance Appraiser does not sell roofing and has no stake in the repair contract. We build an independent estimate and present it to the panel, without promising any particular award. Send your policy and the carrier’s roof estimate through our contact page.
Common questions
Does it really hail in Hawaii?
Rarely, but yes. The March 2012 Windward Oahu supercell produced the largest hailstone on record in the state, and isolated hail occasionally falls during strong storms.
What if my metal roof panel profile is discontinued?
That can affect whether a repair is practical, which is a cost question the appraisal panel can consider. Your policy wording on matching also matters.
Can appraisal include interior water damage from a roof leak?
If the interior damage is part of the covered loss, it can be included. Many policies require that wind first created an opening for rain damage to be covered.