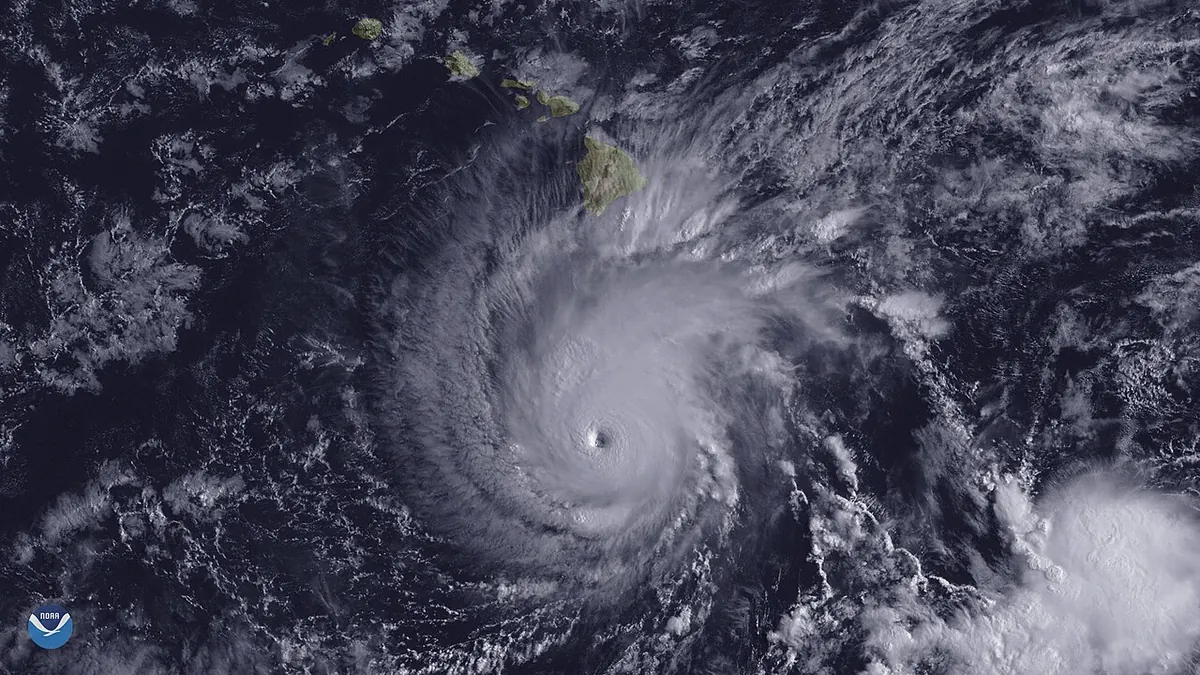
Why hurricane deductibles matter so much here
For many Hawaii homeowners, the hurricane deductible is the single largest number on a storm claim. Unlike a flat all-other-perils deductible, a hurricane deductible is often written as a percentage of dwelling coverage. That means it grows as your coverage limit grows, and on a well-insured home it can easily run into five figures.
Hawaii’s history explains why these deductibles exist. After Hurricane Iniki struck Kauai in 1992, many private carriers pulled back from hurricane coverage, and the state created the Hawaii Hurricane Relief Fund to fill the gap. Once private coverage returned, the fund stopped writing policies. Today hurricane coverage is typically included in, or endorsed onto, a homeowners or condo policy with its own deductible. Policies vary, so the details in yours are what count.
How a percentage deductible is calculated
The basic math is simple: the percentage times the Coverage A (dwelling) limit on your declarations page. Here is an illustrative example only, not a typical figure:
- Dwelling coverage of $800,000 with a 2% hurricane deductible produces a $16,000 deductible.
- The same home with a 5% deductible would carry a $40,000 deductible.
- A flat all-other-perils deductible on the same policy might be only a fraction of either figure.
Some policies calculate the deductible on the dwelling limit alone; others apply it across coverages. Some apply it once per hurricane, others once per policy period. Read the endorsement itself, not just the declarations summary. Our hurricane deductible calculator lets you test different percentages and limits.
What triggers the hurricane deductible
The trigger language is where disputes often start. Common approaches include:
- Damage caused by a storm that has been declared a hurricane by the National Weather Service or Central Pacific Hurricane Center.
- Damage occurring within a defined window before and after a hurricane watch or warning is issued for the islands.
- Damage from wind, wind-driven rain or related causes during a named storm.
Hawaii weather complicates this. A hurricane passing far to the south can still drive strong downslope winds, and a Kona low or tropical storm can cause serious wind and rain damage without ever triggering a hurricane definition. Hurricane Lane in 2018 brought extreme rainfall to the Big Island’s windward side; whether a given policy treated related damage as a hurricane loss depended on that policy’s wording. If your insurer applies the hurricane deductible to damage you believe came from a different event, that is a coverage question to raise in writing – and potentially with a Hawaii attorney.
Condo owners: two deductibles to think about
If you own a condo, the AOAO’s master policy likely carries its own hurricane deductible, sometimes a large percentage of the building’s insured value. When the association absorbs that deductible, it may levy a special assessment on owners. Your HO-6 policy may include loss assessment coverage that helps pay your share, but often with a limit that is lower than people expect, and the coverage may itself be subject to conditions. Our guide to the condo master policy vs HO-6 explains how those pieces fit together.
How the deductible interacts with appraisal
Appraisal decides the amount of loss. In most cases, the deductible is applied after the award, according to the policy. That has a few practical consequences:
- The full loss still matters. Even if a large deductible absorbs much of a claim, an accurate amount of loss can change whether you receive any payment at all, and how much.
- Coverage breakdown matters. If your deductible applies differently to dwelling, other structures and contents, an award that separates figures by coverage makes the final payment easier to calculate.
- Which deductible applies is usually not for the panel. Whether the hurricane deductible or the all-other-perils deductible applies is generally a coverage question. Some panels note facts relevant to that question in the award; how far a panel may go depends on the policy and the law, so ask an attorney.
Before you invoke appraisal on a hurricane claim, compare the gap between your estimate and the insurer’s with the deductible. A modest disagreement on a claim that is mostly absorbed by a percentage deductible may not justify the cost of a full panel.
What to check on your policy today
You do not need a storm on the horizon to prepare. Pull out your declarations page and endorsements and look for:
- The hurricane deductible percentage or amount, and what limit it is calculated on.
- The exact trigger definition and any time window tied to watches or warnings.
- Whether the deductible applies per occurrence or per policy period.
- For condo owners, your HO-6 loss assessment limit and the AOAO’s master policy deductible.
- Whether you have separate flood coverage, since flood and storm surge are generally excluded from homeowners policies.
If anything is unclear, ask your agent to explain it in writing. Questions about how an insurer is handling a claim can also be directed to the Insurance Division of the Department of Commerce and Consumer Affairs.
When to get help
If the insurer has accepted the hurricane claim but you disagree on the repair cost, appraisal may be a good fit. Our hurricane claim appraisal service focuses on valuing the loss accurately, with island pricing for materials, freight and labor. If the dispute is about which deductible applies or whether the damage is covered at all, talk to a Hawaii attorney first.
Quick answers
Is the hurricane deductible applied before or after an appraisal award?
Usually after. The panel sets the amount of loss, and the insurer applies the deductible according to the policy when calculating payment.
Can appraisal decide whether the hurricane deductible applies?
Generally no. Which deductible applies is usually a coverage question, so speak with a Hawaii attorney if you dispute it.
Does my HO-6 cover my share of the AOAO’s hurricane deductible?
It may, through loss assessment coverage, up to the limit and conditions in your policy. Check the limit, since it is often lower than owners expect.